Cost-of-living pressures remain very much with us.
Rising petrol and diesel prices have only reinforced the focus on household budgets, so when it comes to changing cars, it’s little surprise that affordability is firmly on the agenda.
But I think it’s important to recognise that affordability is about more than simply finding the lowest monthly payment.
For dealers and lenders, it is about understanding the customer, their circumstances and the overall cost of ownership, and making sure the finance and vehicle they choose work for them.
What are customers actually looking for?
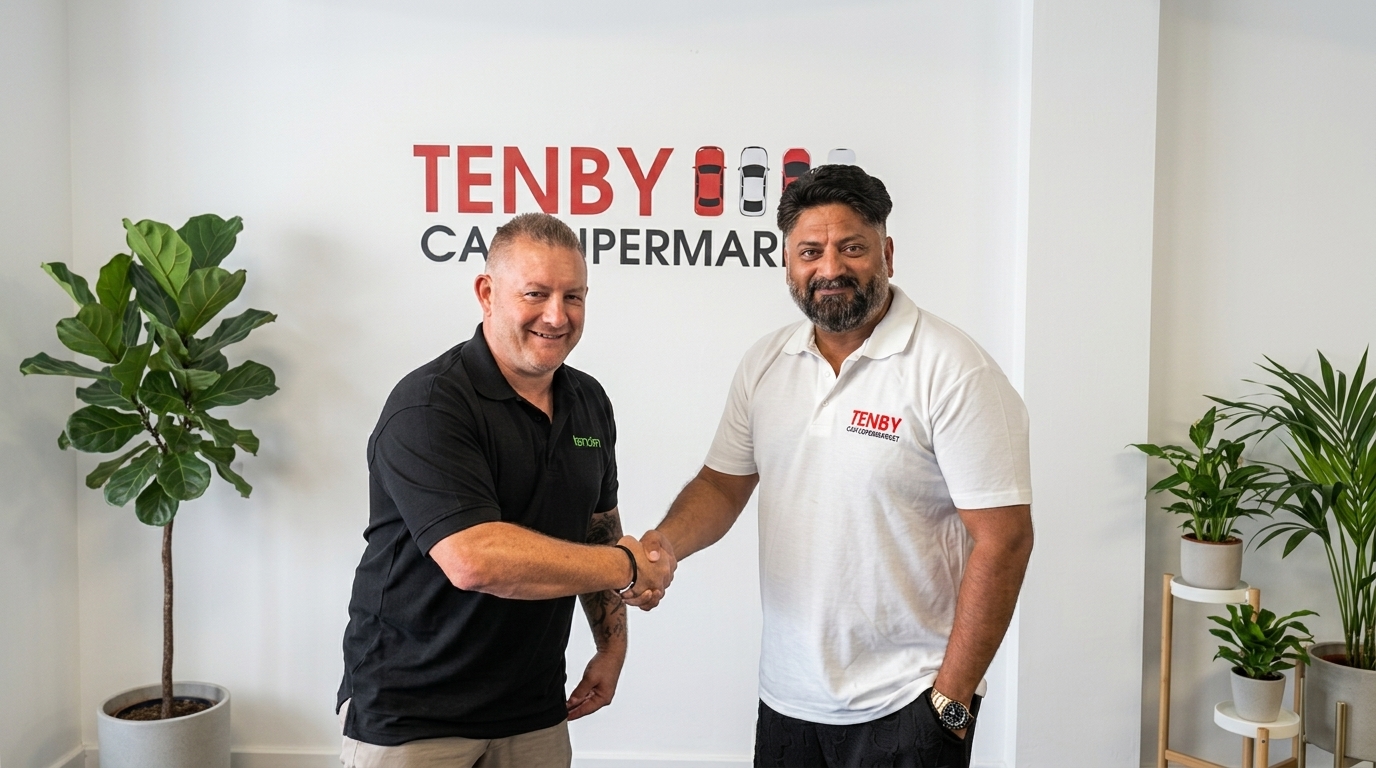
We recently spoke to Shani Gazdar, Director at Tenby Car Supermarket, about what he is seeing from customers.
Tenby specialises in BMW, Audi, Mercedes-Benz and Land Rover SUVs, so you might assume affordability isn't necessarily the first thing on customers' minds.
Shani sees it differently.
“Customers are becoming increasingly price-conscious and are focusing more on monthly affordability than simply choosing the newest or most expensive vehicle.”
I think that's an important observation.
Customers don't necessarily want the cheapest car.
They want a car that works for their lifestyle, fits their budget and represents good value.
That means looking beyond the headline price and considering the wider cost of ownership — including fuel, insurance, servicing, maintenance and, of course, the cost of finance.
Affordability and Consumer Duty
This is particularly relevant in the context of the FCA's Consumer Duty.
For lenders, responsible lending and affordability are fundamental parts of delivering good customer outcomes.
But dealers also have an important role to play in understanding what their customers need and helping them make informed decisions.
That doesn't mean dealers are responsible for underwriting, that's the lender's job.
It does mean that good conversations matter.
Understanding how a customer intends to use the vehicle, what they can comfortably afford and whether the overall proposition makes sense for them can all help support a better outcome.
And I think good dealers have always understood this.
It's about the whole ownership picture
Shani's approach at Tenby is a good example.
He is seeing growing demand for well-priced vehicles that offer customers value for money and manageable monthly payments.
At the same time, the type of vehicle customers choose is changing.
Interest in hybrids is increasing, while demand for fully electric vehicles remains more selective, with customers considering charging availability, battery condition and future resale values.
Diesel also continues to have a role, particularly for higher-mileage drivers and customers who need larger vehicles.
There isn't a one-size-fits-all answer.
The right car for one customer could be completely wrong for another.
That's why the conversation around affordability needs to start with the customer rather than the product.
Good customer outcomes and good business can go hand in hand
One of the things I like about Shani's approach is that he sees doing the right thing for the customer and running a successful dealership as complementary, rather than competing priorities.
As he puts it:
“We are concentrating on vehicles that offer customers strong value for money, affordable monthly payments and a sensible overall ownership cost. Get this right, and it is a win-win situation.”
I think that's exactly right.
Consumer Duty shouldn't be viewed simply as another compliance requirement to work around.
At its best, it reinforces something that good dealers have been doing for years: understand your customer, offer them appropriate choices and make sure the solution you're providing represents genuine value.
The role of a good finance partner
This is where finance providers also have a responsibility.
For us at Tandem, it's about more than having a competitive product.
It's about giving dealers the tools, support and expertise they need to have good conversations with customers and offer suitable finance options.
A good finance partner should make that process straightforward, while maintaining the right balance between commercial reality and strong customer outcomes.
Ultimately, everyone benefits when we get that balance right.
The customer gets a vehicle and finance solution that works for them.
The dealer builds trust and a stronger relationship with their customer.
And the lender becomes a partner rather than simply another name on the finance panel.
Affordability is more than a monthly figure
The motor industry is operating in a challenging environment, and affordability is likely to remain high on the agenda for customers for some time to come.
But I think we need to be careful not to reduce the conversation to one number on a finance quote.
Affordability is about the bigger picture.
It's about the vehicle, the finance, the running costs and whether the overall proposition makes sense for that particular customer.
The best dealers understand that.
And the best finance partners should help them deliver it.
For me, that's what good customer outcomes look like in practice.